EarnIn: Why Wait for Payday?
Activehours Inc.FinanceVerified
- 138.93K Reviews
- 4.7
- Downloads
- 10,000,000+
- Price
- Free
Screenshots
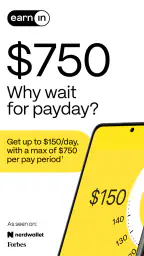
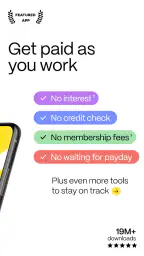
 Analysis by Appwesome
When an expense lands between paychecks, I find it useful to separate two questions: whether the money has already been earned, and whether taking it early will leave enough for later bills. EarnIn is built around the first question. It is a finance app from Activehours Inc. that gives eligible users a way to access part of their pay before payday. I see the appeal, but I’d treat it as a timing tool rather than extra income: a cash-out can ease a short-term squeeze, yet it still comes from a paycheck you will need to manage.
Where a connection matters most
Using a cash-advance app involves more than tapping a button. You need to get through setup, connect the financial and work details the service asks for, and check what is available before deciding whether to move money. Those are moments when a dependable internet connection matters: the app has to communicate with the service and, for a transfer, with the relevant financial systems. I would not plan on completing a time-sensitive cash-out while moving through a dead zone or relying on an unstable connection.
That is especially worth remembering if you are checking your options during a shift or while commuting. A screen that has not refreshed may not reflect your current eligibility or balance, so I would wait until the app has finished loading before making a decision. If the need is urgent, I’d also keep a backup plan in mind rather than assume an attempted transaction has gone through.
Designed for quick checks on a phone
The mobile format makes sense for a service people may consult away from home: you can look at your finances in the same place you handle ordinary banking tasks. EarnIn is free to download, rated for Everyone, and its current version is 16.32, with a minimum OS requirement of 8.0. Those details make it accessible to many phone users, though an older device or operating system that struggles with current apps can make a financial task feel less comfortable than it should.
My practical preference would be to review the available amount and any transfer choices when I have a few quiet minutes, rather than while distracted at a checkout or trying to catch a bus. Small-screen convenience is helpful, but it is easy to focus on the immediate amount and overlook what the next paycheck must still cover. A quick review of upcoming essentials before confirming a cash-out can keep convenience from turning into a tighter week later.
What to do when something does not go through
Financial apps can run into ordinary connection problems: a page may take longer to load, a bank connection may need attention, or a transfer may remain unclear while a status updates. I would avoid repeatedly submitting the same request just because the first screen did not respond immediately. First, check the app’s current status and your bank activity; if the result is still ambiguous, use the in-app support route rather than guessing.
That approach matters because a delayed confirmation and a failed transfer are not necessarily the same thing. Keeping a note of when you tried and what the screen showed can make a support conversation clearer, especially if the issue concerns timing. I would also avoid making another financial commitment on the assumption that the money has arrived until I can actually see the transfer reflected where I need it.
Other Stories to Read




Using mobile data thoughtfully
Checking an advance does not require constant refreshing. I’d open the app when I have a real question, let it complete its checks, and close it once I have a clear answer. That is a sensible habit on a limited mobile plan, and it also reduces the temptation to watch your available amount throughout the day. For account changes or other sensitive actions, I prefer a trusted connection and a private moment rather than public Wi-Fi and a crowded screen.
Because this is a finance tool, I would also keep my phone’s lock screen and app access in mind. A device shared with family or left unlocked at work deserves more care than a casual shopping app. This is not a claim about a particular setting in EarnIn; it is a general way I handle any app that touches my pay and bank activity.
What is EarnIn?
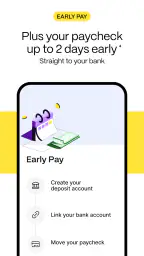
EarnIn is an app that lets you access your paycheck before your official payday. It's like having a financial safety net in your pocket, ready to catch you when unexpected expenses pop up. The app works by allowing you to cash out a portion of your earnings that you've already worked for but haven't officially received yet. It's a simple concept, but one that can relieve a lot of financial stress.
How Does It Work?
Setting up EarnIn is a breeze. After downloading the app, you'll need to link it to your bank account and provide some employment details. Once everything is set up, the app tracks your work hours and allows you to cash out up to $100 per day, with a weekly cap of $500. The best part? There are no fees or interest. You simply tip what you think is fair.
The app uses location tracking or timesheets to verify your work hours, ensuring that the cash you access is money you've already earned. This feature is particularly handy for hourly workers who might have fluctuating incomes.
User Experience
The user interface is clean and intuitive, making it easy to navigate even for those who aren't tech-savvy. The app provides clear instructions and helpful prompts, ensuring that you're never left scratching your head. It's designed to be user-friendly, with everything you need only a tap or two away.
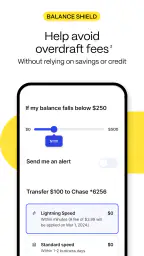
One thing I found particularly useful is the "Balance Shield" feature. It sends alerts when your bank balance is low, and you can even set it up to automatically cash out a small amount if your funds dip below a certain threshold. It's like having a financial guardian angel watching over your shoulder.
Security
Security is a big deal when it comes to financial apps, and EarnIn takes it seriously. The app uses bank-level encryption to protect your information, and it doesn't store your bank login credentials. Knowing that your data is safe adds a layer of comfort when using the app.
Community and Support
One of the standout features of EarnIn is its community aspect. The "Boosts" feature allows friends and family to give you a boost in your max cash-out limit, which can be incredibly helpful in tight situations. It's like having a supportive community right at your fingertips.
Customer support is another area where the app shines. The response times are quick, and the support staff are genuinely helpful, which is a breath of fresh air compared to the automated responses you often encounter with other apps.
Who Can Benefit?
While EarnIn can be beneficial for anyone needing quick access to cash, it's particularly helpful for hourly workers and those with variable incomes. If you're someone who occasionally finds yourself short on cash between paychecks, this app can provide the breathing room you need without the stress of high-interest payday loans.
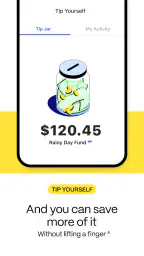
It's also a great tool for those looking to improve their financial habits. By avoiding overdraft fees and managing cash flow more effectively, users can gain better control over their finances.
A useful bridge, not a bigger paycheck
In an everyday situation, imagine your car needs a minor repair a few days before payday, and delaying it would make getting to work difficult. If you have already earned enough and the app offers an amount that fits your situation, an early cash-out could bridge that gap. I would first compare the repair cost with the money still needed for rent, food, and other bills after payday. The useful question is not simply “Can I get this money now?” but “Will taking it now make the next few days safer without leaving a shortfall later?”
That distinction is why I would use the app for occasional timing mismatches, not as a routine substitute for budgeting or a lasting fix for income that does not cover expenses. If an advance becomes necessary every pay cycle, it may be a sign to revisit bill dates, recurring costs, or available workplace options. An advance can smooth a rough week, but it cannot increase the total pay available across the period.
How it fits beside other options
Compared with a credit card, EarnIn is aimed at accessing pay already earned rather than borrowing against a revolving credit line. That can feel more straightforward for someone who wants to avoid carrying a card balance, but it also means the amount is tied to work and eligibility rather than an open-ended limit. A bank overdraft may cover a payment automatically, yet the resulting charges can make it an expensive accident; checking an advance in advance gives you more control, though it still needs careful planning.
Traditional payday loans are another familiar alternative, but I would be cautious about any high-cost borrowing. EarnIn’s model is different from taking a conventional loan, while optional tips still deserve thought: “optional” does not mean irrelevant to your personal budget. If you have savings you can use without jeopardizing an emergency reserve, or a biller that can move a due date without a charge, those choices may be simpler. The best option depends on the actual cost, timing, and effect on your next paycheck.
Limits, eligibility, and habits that matter
The app’s current summary describes access of up to $150 a day, capped at $1,000 per pay period. Those are ceilings, not a promise that every user can withdraw that amount whenever they want. I would check the amount shown for my own account and treat it as a personal limit that may be lower. That prevents a common planning mistake: building a budget around the maximum headline figure before confirming what is actually available.
For hourly workers, work verification is a practical part of the experience, not just background setup. If schedules change, records are incomplete, or work details need updating, the amount available may not line up with what you expected at that moment. I would check eligibility well before a bill is due and keep the relevant work information current. This is more useful than waiting until the final hour and discovering that a verification step needs attention.
The app has a 4.7 average from around 286,000 ratings, and it has been installed over 10 million times. That broad adoption is reassuring as a sign that many people have tried it, but ratings cannot tell me whether it fits a particular employer, bank, work pattern, or budget. I’d still judge it by whether the amount and timing shown in my own account solve a specific need without creating another one.
Who should choose another route
I would skip EarnIn if I need a guaranteed amount immediately, cannot comfortably manage a smaller next paycheck, or would be tempted to withdraw simply because money is visible. It is also not the right fix for a long-running gap between income and essential expenses. In those situations, talking with a bill provider about timing, looking for local financial counseling, or comparing lower-cost forms of credit may be more appropriate than repeatedly pulling pay forward.
It is most compelling for someone with regular work and a temporary mismatch between when a necessary expense arrives and when wages land. People with unpredictable employment, limited access to a reliable phone connection, or discomfort sharing financial and employment information may prefer another approach. The setup itself asks for trust and attention, so I would not rush through it just because the app is easy to download.
Final Thoughts
Overall, EarnIn is a solid app that delivers on its promise to help people access their hard-earned money when they need it most. It's user-friendly, secure, and supported by a community-oriented approach that sets it apart from traditional financial services.
If you're tired of waiting for payday and want a flexible, fee-free way to get your money sooner, EarnIn might just be the app you didn't know you needed. It's about time someone made payday work for you, not the other way around!
My connectivity verdict
For me, EarnIn’s phone-first convenience is strongest when I can check calmly, confirm what is available, and decide how an early payment fits the rest of my pay period. A connection issue does not change the underlying budget trade-off, but it can make a time-sensitive decision harder, so I would not rely on a last-minute check as my only plan. The sensible routine is to look ahead, verify the amount and status before counting on it, and keep an alternative for urgent bills.
As a finance app, it has a clear role: helping eligible workers handle a short gap between earning money and receiving it. I’d recommend it to a friend who understands that distinction and wants another cash-flow option, while reminding them to check the next paycheck’s obligations before accepting an advance. Used with that restraint, it can offer breathing room; used as a way to stretch income indefinitely, it is unlikely to solve the real problem.
Highlights
- Instant access to earned wages.
- No interest or hidden fees.
- User-friendly interface.
- Budgeting tools included.
- Helps avoid payday loan traps.
Limitations
- Limited cash-out amounts.
- Requires bank account linkage.
- Not available in all states.
- Data privacy concerns.
- May encourage overspending.
Frequently Asked Questions
01What is EarnIn and how does it work?
EarnIn is a financial app designed to give users access to their earned wages before payday. It works by linking to your bank account and tracking your work hours through timesheets or location services. You can then withdraw a portion of your earned wages, which are automatically deducted on payday.
02Is EarnIn safe to use with my bank account?
Yes, EarnIn uses bank-level security to protect your financial data. The app employs encryption and other security measures to ensure your personal and banking information remains secure. Users should always use strong passwords and monitor their accounts for any unauthorized transactions.
03Are there any fees associated with using EarnIn?
EarnIn does not charge mandatory fees. Instead, it operates on a voluntary tipping system, allowing users to tip an amount they feel is fair for the service. However, it's important to consider your financial situation and tip responsibly to avoid overspending.
04What are the withdrawal limits with EarnIn?
EarnIn typically allows users to withdraw up to $100 per day and $500 per pay period. These limits can vary based on your usage history and other factors. It's advisable to check the app for your specific withdrawal limits and plan your finances accordingly.
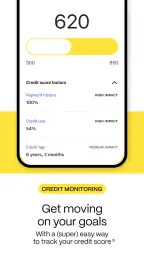
05Does using EarnIn affect my credit score?
No, using EarnIn does not impact your credit score. The app does not perform credit checks or report activity to credit bureaus. It simply allows you access to your earned wages without affecting your credit history or score.


